Thursday, October 15, 2026Developing PakistanIslamabad
Long-form reporting, sector deep-dives, and analytical dispatches on the forces shaping Pakistan's economy.
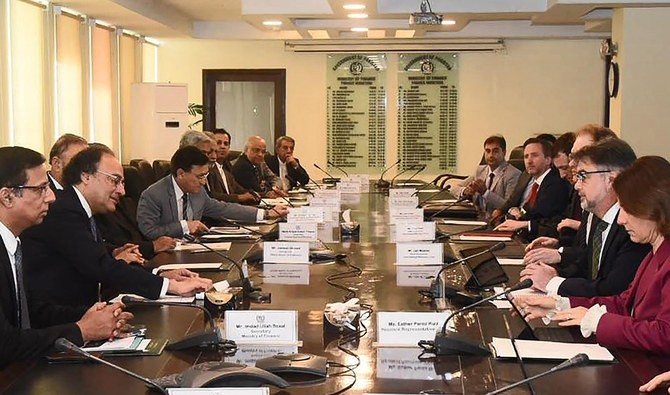
The $3 billion Stand-By Arrangement has restored credibility and unlocked multilateral inflows. It has also enforced a growth ceiling of 2–2.5% while structural reforms lag.
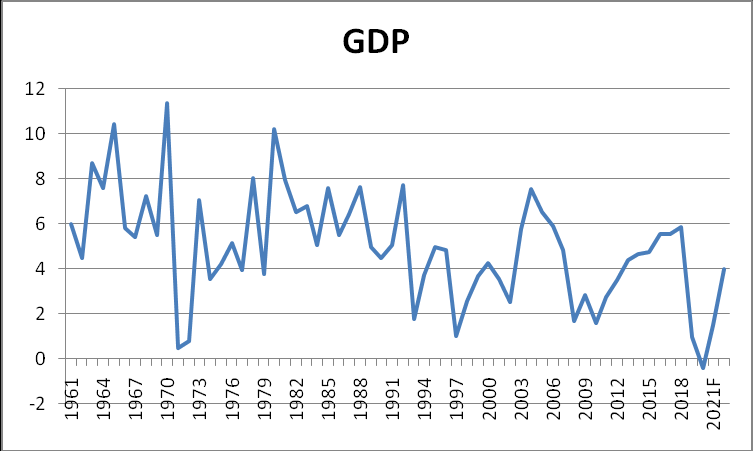
Growth has settled into a low-equilibrium band far below the 4–5% historical average. Stability is real. Recovery isn't.
FDI inflows have crossed $1.2–1.4 billion annualised. It's a re-entry phase, not a full recovery — but investor mood has clearly turned.
Foreigners have returned to the KSE-100, but flows are tactical — $50–100M in and easily reversible. Liquidity is back. Long-term commitment isn't.
Total investment is still below 15% of GDP versus 25–30% in emerging Asia. Predictability, not liquidity, is the missing input.
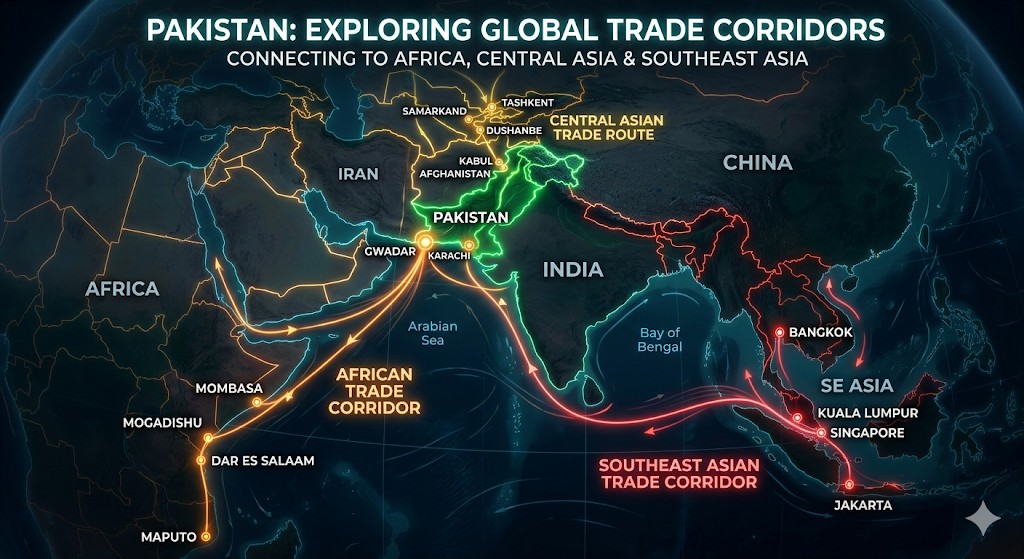
Phase two of CPEC is about SEZs, manufacturing and B2B linkages — not highways. Trade with China has crossed $25B, but the balance is still one-sided.
Domestic sales are down 10–15% while installed capacity has crossed 80 million tons. Utilisation below 60% is squeezing everyone but the export-ready majors.